Earnest Money in Oregon: What It Is and When You Could Lose It

TL;DR
What is earnest money and when do you lose it? Earnest money is a good-faith deposit showing you intend to buy, held by a neutral third party until closing, where it's credited toward your down payment. You lose it by missing written notice deadlines on contingencies, backing out for reasons not covered by an active contingency, or proceeding after waiving protection, not by inspection findings alone.
- Earnest money is your money the whole time, typically 1-3 percent of purchase price, deposited into escrow within three business days.
- Contingencies protect your deposit only if you send written notice before the deadline; missing the date is what puts deposits at risk, not the inspection report itself.
- Track your contract's Effective Date and add the specified contingency days (noting calendar vs. business days) to know your exact written notice deadline.
- Deposit is lost when you waive contingencies, back out for unprotected reasons, or fail to act in writing within the contingency window.
Earnest money is the deposit you put down to show a seller you're serious about buying their home, and it's not a fee, a down payment, or a gift. It's your money the whole time. It gets held by a neutral third party, and it comes back to you as long as you handle your contingency deadlines correctly. Honestly, that last part is the piece almost nobody explains clearly, so let's start there.
My actual position after 300+ closings is this: a long or scary inspection report is not what puts your earnest money at risk. An unmanaged deadline is. I've watched buyers panic over a 12-page inspection report like the report itself was the danger, when the report has almost nothing to do with whether they keep their deposit. What matters is whether someone sends written notice on time, tracks the actual dates in the contract, and knows which contingency covers which problem. That's the job. Let's walk through it.
What Earnest Money Actually Is (and What It Isn't)
Earnest money is a good-faith deposit that tells the seller you intend to follow through on your offer. It's not your down payment, though it usually gets credited toward it at closing. It's not a fee the seller keeps for reviewing your offer. And it's definitely not something the seller can just grab if they don't like how negotiations are going.
In Salem-Keizer, I typically see earnest money land somewhere between 1 to 3 percent of the purchase price, though there's no state law that sets a required amount (source). The amount is negotiable between buyer and seller, and it's part of what makes an offer feel strong or weak to a seller reviewing multiple offers.
Where the Money Goes: Escrow, Trust Accounts, and Who Can Touch It
Once your offer is accepted, your earnest money doesn't sit in your agent's desk drawer or the seller's bank account. Oregon administrative rule requires a real estate broker or principal broker to deposit your earnest money check into a clients' trust account or a licensed neutral escrow depository within three banking days of offer acceptance (source). In most Salem-Keizer transactions, that means it goes to a title company acting as escrow.
This matters more than people realize. Under Oregon's escrow statute, an escrow agent cannot release earnest money to one party just because that party asks for it (source). If a deal falls apart and buyer and seller disagree about who's entitled to the deposit, the escrow company holds the funds until both parties sign a mutual release or a court sorts it out. Neither side gets to unilaterally decide they're right. That's a good thing. It's what keeps your deposit safe from a seller who gets frustrated and tries to claim it without cause.
The Contingencies That Keep Your Deposit Safe (and What "Protected" Actually Requires)
A standard Oregon purchase agreement includes contingency periods: inspection, financing, appraisal, and sometimes title. Each one gives you a defined window to investigate something and back out with your earnest money intact, as long as you act within that window.
This is the part that gets glossed over in most explainers I've read: a contingency doesn't protect you just by existing on the page. It protects you only if you use it correctly. That means:
- Reading and understanding the actual deadline dates in your specific contract, not a generic "10-day inspection period" someone mentioned in passing
- Sending written notice, not a phone call or a text to your agent saying you're thinking about backing out
- Sending that notice before the deadline, not the same day at 11:58 p.m. after a long debate about what to do
- Making sure the issue you're worried about is actually covered by a contingency you still have open
On the standard Oregon offer form (OREF 001), for example, the appraisal contingency defaults to 20 business days from the Effective Date if that field is left blank (source). Business days, not calendar days. I've seen buyers assume "20 days" meant three weeks and miscounted by almost a week. That kind of miscount is exactly how deposits get put at risk, and it has nothing to do with what the appraisal actually said.
If you want a deeper walkthrough of how the inspection piece specifically works, I've written about how inspection contingencies protect your earnest money in more detail, including what "material defect" actually means in practice.
The Real Ways Buyers Lose Earnest Money
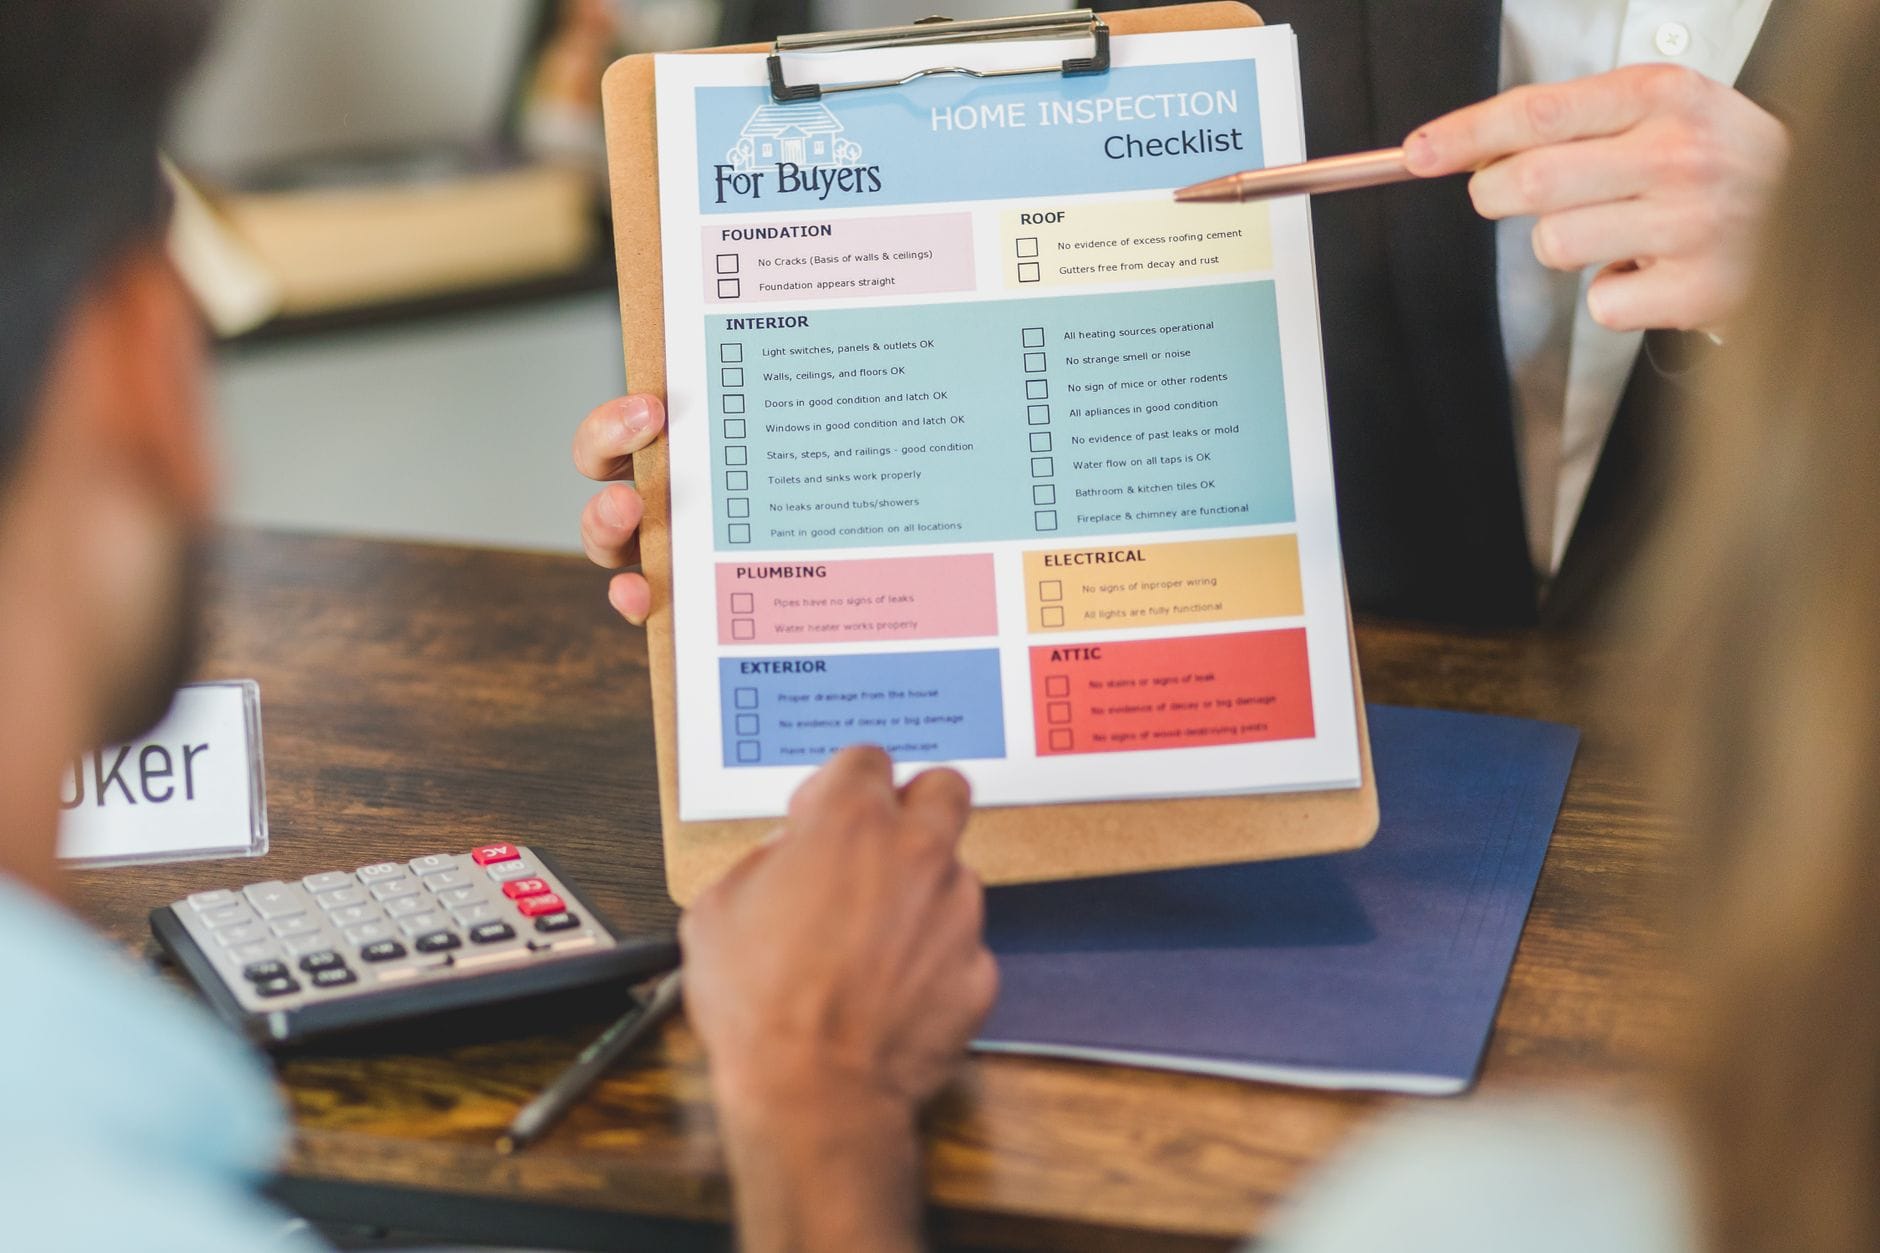
This is the section I wish more people read before they got nervous about a scary-looking report. In my experience, buyers almost never lose earnest money because an inspection found problems. They lose it when:
- They miss a written notice deadline. The contingency period expires, the buyer hasn't sent anything in writing, and legally the contingency is treated as waived.
- They try to back out for a reason with no contingency covering it. Cold feet, a better house down the street, a family member's opinion. None of those are protected reasons once your contingencies have expired or don't apply.
- They proceed anyway and then try to walk. If you remove your financing contingency and then can't get a loan, that's a different situation than if the contingency was still active.
- They assume "nonrefundable" language is automatically enforceable. Some contracts include language calling earnest money nonrefundable under certain conditions, but a clause that functions as a penalty rather than a reasonable estimate of damages isn't always enforceable. This is a legal question, not a real estate one, and it's worth a conversation with an attorney if you're ever staring down that exact clause.
I worked with a buyer whose inspection turned up a home that needed a new roof, a new sewer line, and additional repairs, right after they'd already negotiated seller-paid closing costs and prepaids, which left very little room to also ask for repair credits. That report was long. It was not a small list. But the deposit was never actually at risk, because we were inside the inspection period, we had it in writing, and we worked the report line by line: what each issue meant, what it would cost, and whether it was reasonable to ask the seller to address it. We coordinated the sewer, drainage, and electrical concerns and closed with everything fixed before move-in. The scary report wasn't the threat. Managing the deadline and the negotiation was the actual work that protected their money and got them a move-in ready home.
If you're trying to understand what an inspector is actually checking (and what they're not), that's a good place to start before your own inspection day arrives.
A Simple Way to Track Your Own Deadlines
The formula I'd want any buyer to use, whether or not they're working with me, is simple: take your contract's Effective Date, then add the number of days specified for each contingency (inspection, financing, appraisal, title), noting whether your contract says calendar days or business days.
Say your Effective Date is September 22, and your inspection contingency is 10 calendar days. Your written notice needs to be sent by October 2. If your appraisal contingency defaults to 20 business days because that field was left blank on an OREF 001 form, you'd count only weekdays from September 22, landing closer to October 20 depending on holidays.
I'd never tell a buyer to trust my math over their actual signed agreement. Always confirm your exact deadlines and whether your contract uses calendar or business days with your agent or your escrow officer before you rely on any date, including the ones in this example.
What Happens at Closing
If everything goes as planned, your earnest money doesn't get refunded to you separately at closing. It gets credited toward your down payment and closing costs, showing up as a line item on your settlement statement. If you want a fuller picture of what other costs show up alongside it, take a look at how escrow and closing costs work in local transactions.
And if a deal does start wobbling, whether it's a contingency question, a title issue, or something that feels bigger than a simple repair negotiation, my rule is simple: don't guess. If a boundary or title question comes up that I can't answer with full confidence, I bring in a surveyor, a title company, or an attorney rather than pretending I have every answer. That's not a weakness in the process. That's the process working correctly.
Questions people ask
What happens if we find something wrong with the sewer, the roof, or another major item?
As long as you're still inside your inspection contingency period and you send written notice on time, finding a major issue doesn't threaten your earnest money at all. It becomes a negotiation: what the repair actually costs, whether it's reasonable to ask the seller to fix it or credit you, and how it fits with whatever else you've already negotiated in the deal. I go through this line by line with every report I work.
Is this inspection report as bad as it looks? Should we ask the seller to fix this, or is that asking too much?
Almost every home has something on the inspection report. My advice is always to ask three questions before reacting: what does this issue actually mean, what would it cost to address, and is it reasonable to ask the seller to handle it given the rest of your offer. A long report is not a reason to panic or to walk away by itself.
How much are closing costs and prepaids actually going to be, and can we ask the seller to pay all of them?
Closing costs and prepaids vary by loan type, purchase price, and lender, so I'd never quote a flat percentage without looking at your specific numbers. Asking a seller to cover some or all of them is a normal, negotiable part of many Salem-Keizer offers, and whether it's realistic depends on your price point and how competitive the listing is.
Earnest money can feel like the scariest number on the whole contract when you're a first-time buyer, and honestly, I get why. But once you understand that it's your money, held by a neutral third party, protected by contingencies you actively manage rather than passively rely on, it stops being scary and starts being just another part of the timeline. If you want to see how earnest money fits into the bigger picture, I've also written about the full timeline from offer acceptance to closing.
If you're working through an offer right now and want to talk through your specific contingency dates or strategy, feel free to connect with me and start your home search. No pressure, just information.
Hannah Fouts-Sparks
Broker, Sparks Property Group at SMI Real Estate. Licensed in Oregon. Serving Keizer, Salem, and the Willamette Valley.
Hannah@SparksPropertyGroup.com · 971.218.6225
Connect with Sparks Property Group ↗
Member discussion