Rate Buydowns in Salem-Keizer: When They Actually Pay Off
TL;DR
Should you buy down your mortgage rate? Only if the breakeven math works for your timeline and that same credit wouldn't do more toward price, closing costs, or repairs.
- Permanent points buydown: cost divided by monthly savings equals breakeven months.
- Temporary 2-1 buydown: ask if you can absorb full payment in year three.
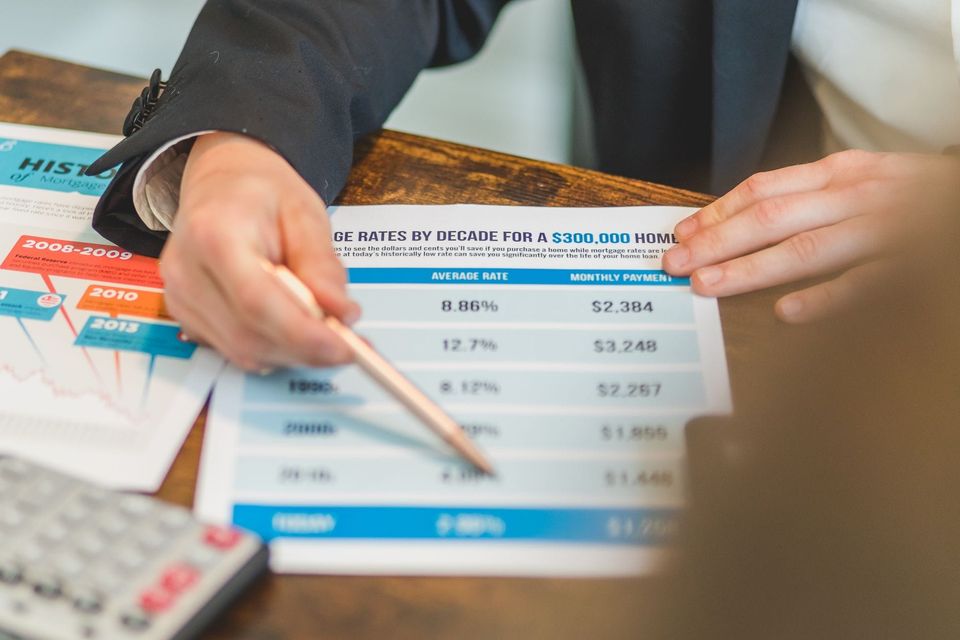
Should you take a seller- or builder-offered rate buydown right now? My honest answer: only after you run the math on what it actually costs, what it actually saves you, and whether that same credit might do more for you somewhere else in the deal. A buydown isn't a gift the seller is handing you out of goodwill. It's a negotiable dollar amount, and I think it deserves the same line-by-line scrutiny I give an inspection report, not a rubber stamp.
That's the whole thesis of this post, so let me say it plainly before we get into the mechanics. Clearing a breakeven formula doesn't automatically make a buydown worth it. The real question is whether this specific credit, applied this specific way, gets you more than that same credit would get you if it went toward price, closing costs, or prepaids instead. Most articles on this topic stop at the formula. I want to go one step further.
What a Rate Buydown Actually Is (and Isn't a Gift)
A rate buydown is money, usually from a builder or a seller, paid upfront to temporarily or permanently lower your mortgage interest rate. It shows up as a credit at closing. That credit has to come from somewhere, which almost always means it's coming out of the total dollars the seller or builder was willing to put into your transaction in the first place.
Here's why this is on buyers' minds this fall. Rates have stayed elevated through the end of September and into October 2026, with Freddie Mac's survey showing 7.28% as of October 1, compared to 6.34% a year earlier (Freddie Mac, via Trading Economics). When rates sit this high, sellers and builders look for ways to make a monthly payment feel more approachable, and a buydown is one of the tools they reach for.
I'll be honest about what I can't tell you here. WVMLS, the MLS that covers roughly 95% of Salem-Keizer listings, doesn't publicly track how often sellers or builders are offering buydowns, or what those credits typically cost on local new construction. That data simply isn't published anywhere I can verify. What I can tell you is that I'm seeing these credits show up more often in offers I'm writing and reviewing this fall, and if you want a sense of what's being offered on a specific property or in a specific new-construction community, that's exactly the kind of thing I can pull comps on for you.
Temporary 2-1 Buydown vs. Permanent Points Buydown: How Each Works
These are two very different tools, and mixing them up is where a lot of confusion starts.
- Temporary 2-1 buydown: Your payment is calculated at roughly 2% below the note rate in year one, 1% below in year two, then the full note rate from year three forward (Norada Real Estate). It's funded by a lump-sum credit at closing, and it runs out on a schedule no matter what you do.
- Permanent points buydown: You (or the seller, on your behalf) pay discount points upfront to permanently lower the note rate for the life of the loan. Generally, one point costs 1% of your loan amount and buys roughly a 0.25% rate reduction, though your lender's exact pricing will vary.
The 2-1 is really prepaid interest relief with an expiration date. The permanent buydown is a trade: cash now for a lower rate for as long as you hold the loan. Those are different bets, and they deserve different questions.
The Breakeven Math to Ask Your Lender to Run
For a permanent buydown, the formula is simple: cost of the points divided by your monthly payment savings equals the number of months to break even. Industry examples routinely land around a 60-month breakeven whether you're buying half a point, one point, or two, on a loan near $400,000 (Yahoo Finance). Your actual number will depend on your loan amount and your lender's specific pricing, which is why I always tell buyers to ask their loan officer to run it on their real numbers, not a generic chart.
Let's walk through a clearly hypothetical example so the formula makes sense on paper. Say you're financing $420,000. One point costs 1% of that loan amount, or $4,200, and might buy you about a 0.25% rate reduction. If that knocks roughly $65 off your monthly payment, you'd divide $4,200 by $65 and land around 64 months to break even, a little over five years. If you expect to keep this loan past that point, the math works in your favor. If you think there's a real chance you'll sell or refinance before year five, you haven't recovered your cost yet.
A 2-1 buydown doesn't really have a breakeven date, since it's consumed within two years no matter how long you keep the loan. Instead, add up the total relief. Say a builder offers a $12,000 credit to fund a 2-1 on that same $420,000 loan. If your payment runs about $350 lower per month in year one and $175 lower in year two, that's $4,200 of relief in year one and $2,100 in year two, or $6,300 total against a $12,000 credit. The real question for a temporary buydown isn't "did I break even." It's "can my budget absorb the full payment starting in year three," and "was $12,000 in credit the best use of that seller's money, or would $12,000 off the price have done more?"
I built a simple breakeven calculator into this guide so you can plug in your own loan amount, the buydown type, the upfront cost, your monthly savings, and how long you expect to keep the loan, rather than eyeballing someone else's example. Worth checking out before you make a decision either way.
When a Buydown Is Worth It, and When the Money Is Better Spent Elsewhere
I wouldn't tell every buyer to take the buydown, and I wouldn't tell every buyer to turn it down either. It genuinely depends on your plans for the house and the loan.
A permanent buydown tends to make more sense when this is a longer-term hold for you, the kind of house where you can picture staying past that five-or-so-year breakeven point. A 2-1 buydown tends to make more sense when you have real reason to believe your income will rise or your other debts will drop before year three, so the step-up to the full note rate doesn't catch you off guard.
Where I'd pump the brakes: if you're planning to sell or refinance within three to four years, if the buydown credit is eating into what could otherwise cover closing costs and prepaids, or if the seller's total concession is capped and you're choosing a buydown over help with those upfront cash needs. In those cases, the same dollars applied to price or to closing costs might serve you better than a rate that only helps for a window you may not even be in the loan long enough to use.
This is also a good moment to get pre-approved and talk through your actual numbers before you start exploring financing options, since a lender who's already run your file can tell you quickly whether a buydown changes your qualifying picture at all. And if you're trying to figure out where rates might be headed before locking in a strategy, I'd point you to this piece on understanding how rates affect your buying power.
How Buydown Credits Fit Into Negotiating Your Offer
Here's where my own approach comes in. I work a repair credit the same way I work an inspection report: line by line, asking what it costs, what it actually gets my client, and whether there's a better use of that same money. A buydown is no different. It's just a line item that happens to be about the rate instead of the roof.
I've had buyers negotiate seller-paid closing costs and prepaids into their offer, only to find in inspection that the home needed a new roof and a new sewer line, with little cash left to address it. We worked that report line by line, negotiated the repairs, and coordinated the roofing, drainage, and electrical work so everything was fixed before move-in (I wrote more about that negotiation in deciding between repairs, credits, or renegotiating terms). The lesson applies here too: once the seller or builder's total concession is spent on a buydown, it's spent. It's not available for the sewer line, the roof, or the closing costs you'll need regardless of your rate.
Credits and concessions show up in your purchase agreement the same way earnest money does, as specific negotiated terms, not automatic add-ons. If you want a plainer explanation of how those terms get written into an Oregon offer, this guide on understanding how credits and concessions appear in offers is a good place to start.
My rule of thumb: before you accept a buydown as presented, ask your agent and your loan officer whether the same dollar amount could be redirected toward price reduction, closing costs, or prepaids, and run the numbers on all three before you decide. Don't assume the version on the table is the only version available.
I'm not a lender, and I wouldn't pretend to run your exact numbers for you. This is a conversation for a licensed loan officer who can see your actual loan amount, your credit profile, and your rate options side by side. What I can do is help you negotiate whether that credit exists in the first place, and how it fits into the rest of your offer.
Questions people ask
Do you think now is actually a good time to buy, or should I wait?
I wouldn't try to time the market perfectly, and honestly, I don't think anyone can. What matters more is your own timing: your job, your savings, your plans for the next several years. Rates sitting above 7% this fall are exactly why buydown credits are showing up more, so if the right house comes along, it's worth looking at your real numbers rather than waiting on a headline.
What happens if the appraisal comes in low?
If the appraisal comes in under the purchase price, you generally have a few options: renegotiate the price with the seller, bring additional cash to closing to cover the gap, or in some cases challenge the appraisal with additional comps. Which option makes sense depends on your loan type and how much flexibility is in your contract, so this is a conversation to have with your lender and agent together as soon as the appraisal comes back.
How do I know if I chose the right realtor, lender, and loan type?
A good sign is whether they're walking you through tradeoffs, like buydown versus price reduction, rather than just presenting one option as the obvious choice. I'd want a lender who's willing to run multiple scenarios for you and a loan officer who explains the math rather than just the monthly payment. If anyone involved seems rushed to get you to a decision, that's worth noticing too.
Buydowns are one more piece of the puzzle, not the whole decision. I think the best move is to treat every dollar a seller or builder offers you as negotiable, run your real numbers with a licensed loan officer, and then come talk through strategy with me before you write the offer. No pressure, just information, and I'm always happy to look at a specific scenario with you. You can find everything, including how to reach me, at my Linktree, or just reach out anytime.
Hannah Fouts-Sparks
Broker, Sparks Property Group at SMI Real Estate. Licensed in Oregon. Serving Keizer, Salem, and the Willamette Valley.
Hannah@SparksPropertyGroup.com · 971.218.6225
Connect with Sparks Property Group ↗
Member discussion