Fixer-Upper or Move-In Ready in Salem-Keizer: True Costs
TL;DR
In Salem-Keizer, a fixer-upper listed lower than a move-in ready home often costs more once you add renovation expenses, Oregon's above-average labor costs, financing friction, and carrying costs during the rehab period. For example, a $420,000 fixer-upper with a $60,000 contractor bid, 15% contingency, four months of carrying costs, and appraisal-gap buffer totals $507,800, exceeding a $475,000 move-in ready home. The only accurate way to decide is to run the actual math on your two specific properties before writing an offer.
- Oregon construction labor costs run above the national average; standard kitchen remodels in Salem range $8,264 to $41,324 depending on scope.
- Renovation loans come with draw schedules, appraisal gaps on unfinished work, and carrying costs that don't appear in contractor bids.
- Move-in ready homes offer price certainty and no renovation financing risk; Salem-Keizer homes closed at 99.7% of list price in August 2026.
- Hidden inspection findings can eliminate negotiating room if closing cost credits were already built into the offer.
- Calculate total fixer-upper cost as purchase price plus renovation bids, contingency, monthly carrying costs, and appraisal buffer, then compare directly to move-in ready price.
The home with the lower price tag isn't always the cheaper one once you add everything up. In my experience, a "discounted" fixer-upper in Salem-Keizer can end up costing more than a similarly priced move-in ready home once you factor in Oregon's labor costs, financing hurdles, and carrying costs during the rehab period. The only way to know for sure is to run the actual numbers on the two specific houses you're comparing, not a general rule of thumb.
This isn't a post about whether fixer-uppers are good or bad. It's about giving you a real math exercise to run before you write an offer on either one, because price per square foot and list price alone never tell you what a specific house is actually going to cost you to own.
Why Comparing List Prices Alone Gets Buyers Into Trouble
Say a fixer-upper is listed at $420,000 and a move-in ready home two streets over is listed at $475,000. On paper, the fixer-upper looks like the better deal by $55,000. But that comparison only works if the $55,000 in "savings" actually covers everything the fixer-upper needs, plus the time, financing, and risk that come with it.
I've watched this play out on actual transactions. A buyer negotiates a lower purchase price, feels good about the discount, and then the inspection report shows a roof and a sewer line that need replacing on top of smaller repairs. By that point, seller-paid closing costs and prepaids have already been negotiated into the offer, so there's very little room left to also ask for repair credits. Understanding how inspection findings affect your real numbers before you're mid-transaction changes how you write the offer in the first place.
What a Fixer-Upper Really Costs in Salem-Keizer
Oregon's construction labor costs run above the national average, which matters a lot once you start pricing out real work instead of estimating from a national calculator.
- Kitchen remodels in Salem average $18,528 to $25,369, with the full range running $8,264 to $41,324 depending on scope and finishes (source).
- A standard 200 square foot kitchen remodel in Oregon runs about $33,930 including a 10% contingency, driven by a labor cost index of 113.1 against a national average of 100 (source).
- For a broader benchmark, a mid-range kitchen-plus-one-bathroom project nationally runs about $49,000 before you layer Oregon's labor premium on top of it (source).
- A full renovation of a roughly 2,000 square foot home can run $200,000 to $500,000 or more, depending on finishes and whether you're moving walls or replacing major systems (source).
Those figures are for finishes and layout work. They don't include permits, which vary by city and scope, and they don't include the surprises that show up once walls are opened. This is exactly why getting at least three contractor bids before you write an offer matters more than a general contingency percentage. A bid tells you what your specific house needs. A percentage guess doesn't.
The Financing Hurdles Nobody Mentions
Renovation loans like an FHA 203(k) or a conventional renovation product exist for a reason, but they come with friction that a lot of general advice skips over.
First, draw schedules. Renovation loan funds typically release in stages as work is completed and inspected, which means you or your contractor need enough cash flow to front costs between draws. Second, appraisal gaps. Lenders on a renovation loan are appraising the home based on projected value after the work is done, and if there aren't good finished comparable sales nearby, that appraisal can come in lower than expected, leaving a gap you have to cover out of pocket mid-project. This is a different risk than the appraisal gap conversation buyers usually have on a move-in ready purchase, and it's worth understanding how financing costs and renovation loans work differently before you assume your rate and terms will look like a standard mortgage.
Third, carrying costs. If the rehab takes four months instead of two, that's four months of a mortgage or rent payment, utilities, and possibly storage or temporary housing, on top of the renovation budget itself. None of that shows up in a contractor's line item bid, but it's real money leaving your account every month the house sits unfinished.
What You're Actually Paying For in a Move-In Ready Home
The premium on a move-in ready home buys certainty. You know the price, you know the timeline (close and move in), and you're not exposed to appraisal gap risk on unfinished work or the chance a contractor's schedule slips by months.
In August 2026, the Salem-Keizer median sales price sat at $449,948, up 3.4% year over year, with 608 active listings and 3.9 months of supply. I track this data every month for my Salem-Keizer market report using WVMLS and Domus Analytics numbers, and one month of data never tells you what a specific property is doing. But it does tell you that move-in ready homes in this price range aren't sitting on rising inventory alone. Buyers are still closing at close to full asking price on well-priced homes, which is worth remembering before assuming a fixer-upper is automatically the better financial move just because inventory has grown.
Real Example: How One Inspection Report Rewrote the Math
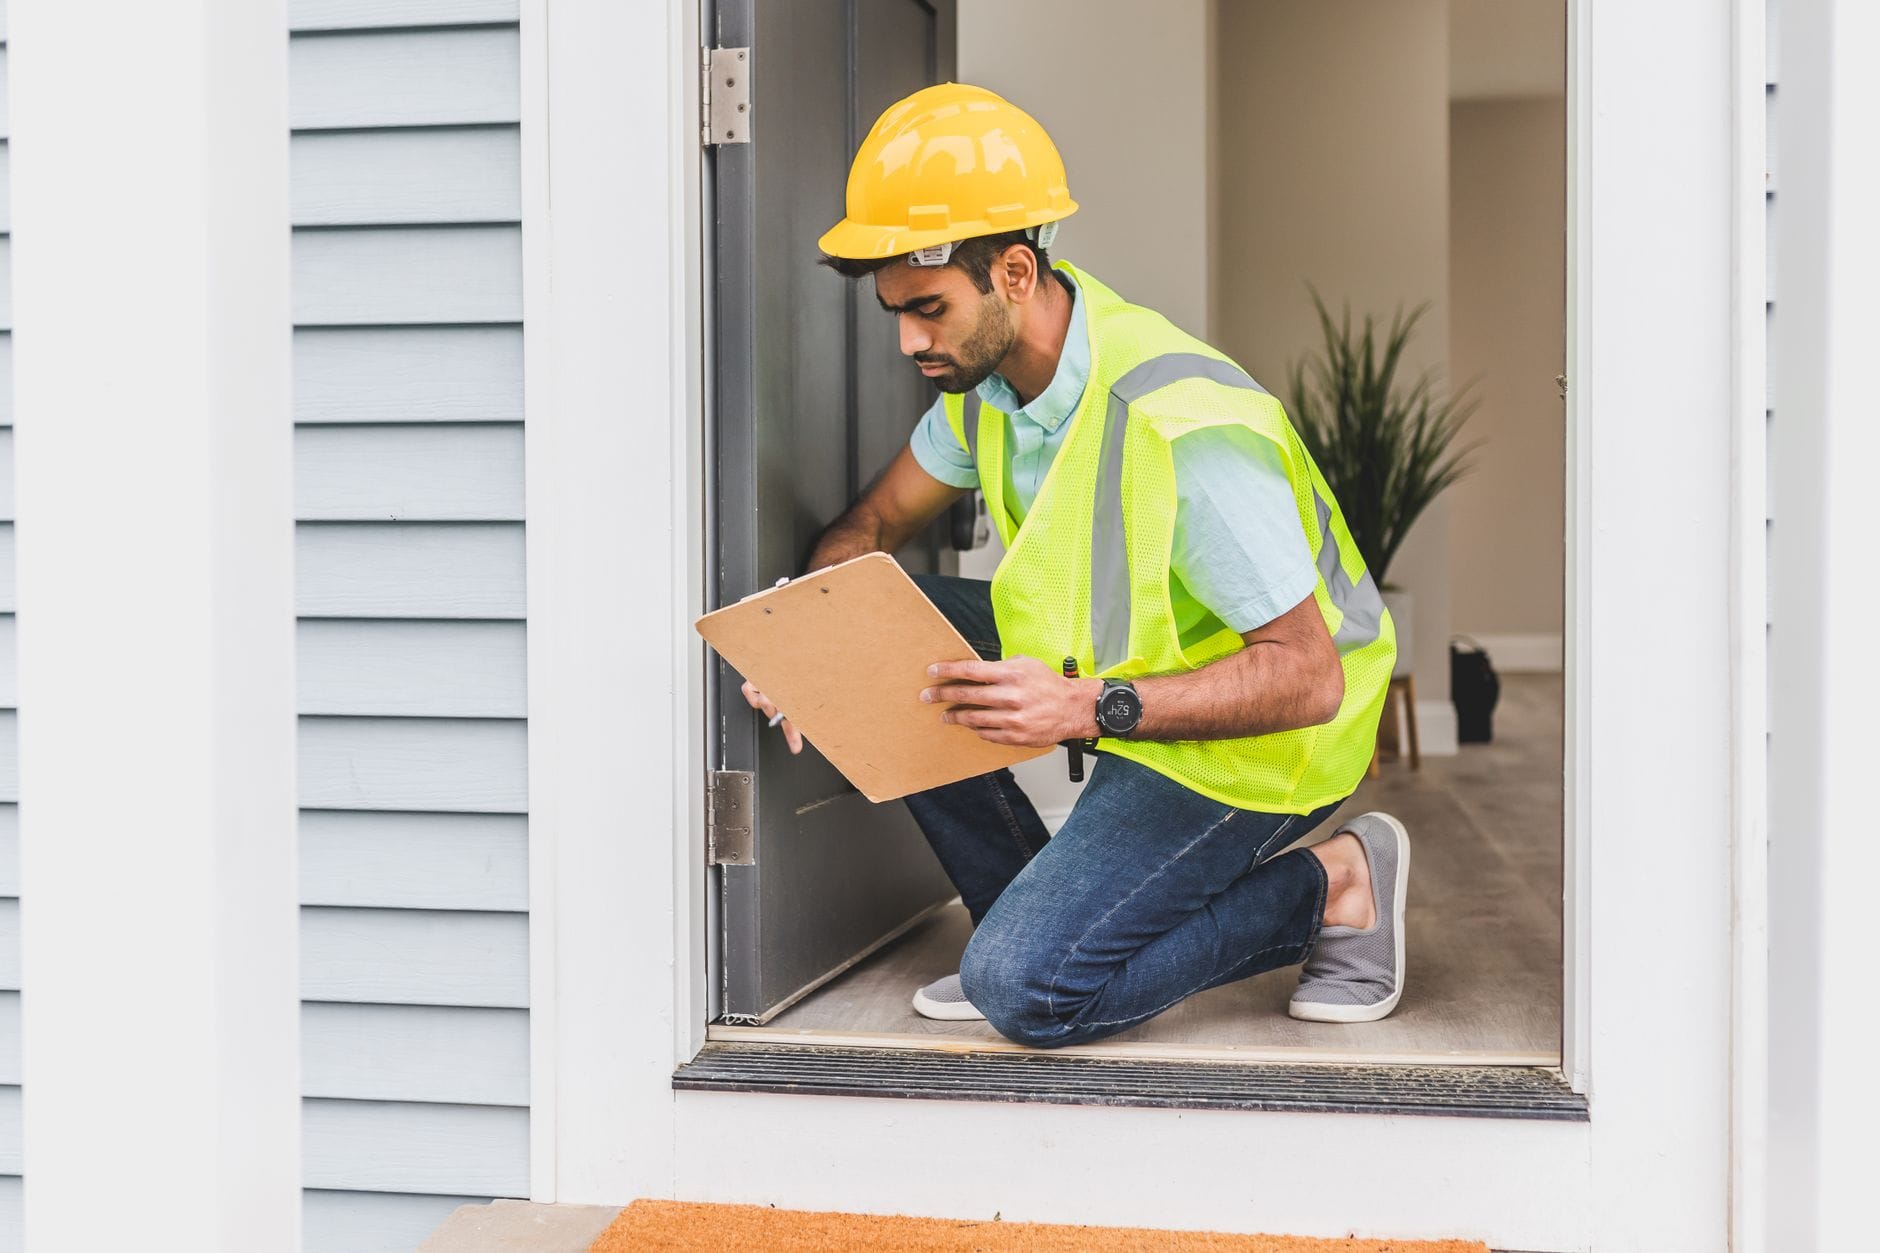
I worked with a buyer who negotiated a purchase price they felt good about, along with seller-paid closing costs and prepaids built into the offer. Once the inspection came back, it showed the home needed a new roof, a new sewer line, and several smaller repairs. Because the closing cost credit had already been negotiated, there wasn't much room left to also ask for a full repair credit on top of it.
We worked the inspection report line by line, ranked what mattered most, and negotiated directly with the seller on the roof and sewer line while coordinating drainage and electrical items with outside contractors. The home closed with everything fixed before move-in, but it took real negotiation, not a simple credit request, to get there. That's the piece a lot of general fixer-upper advice skips: understanding what hidden costs an inspection can reveal matters as much as the contractor bid you get before you write the offer.
Run the Numbers Before You Write an Offer
Here's the plain-language version of the math I'd want you to run on any two specific listings you're comparing:
Total fixer-upper cost = purchase price + renovation line items (roof, sewer or plumbing, electrical, kitchen, bath, other) + (renovation subtotal x contingency percentage, typically 10 to 20%) + (monthly carrying cost x rehab timeline in months) + any appraisal-gap buffer if you're using a renovation loan.
Compare that total directly against the move-in ready purchase price. Whichever number is lower, after everything is added in, is the one that actually costs less.
A hypothetical example to walk through by hand: Say the fixer-upper is $420,000, with a contractor bid of $60,000 covering a roof, kitchen refresh, and bathroom update. Add a 15% contingency ($9,000), four months of carrying costs at $2,200 a month ($8,800), and a $10,000 appraisal-gap buffer on a renovation loan. That totals $507,800, which is higher than a $475,000 move-in ready home two streets over. Change any one of those numbers, the contractor bid, the timeline, or the contingency percentage, and the answer can flip. That's the point: the math has to be run on your specific numbers, not a rule of thumb.
For buyers with strong cash reserves, a locked-in contractor bid, and tolerance for financing risk, a fixer-upper can still come out ahead, especially if the discount is deep enough to absorb Oregon's labor premium. For buyers who want price certainty and don't want appraisal-gap risk hanging over a renovation loan, a move-in ready home in the same price range is usually the more predictable choice. Neither answer is universal. It depends on the specific bids, the specific timeline, and how much risk you can actually carry. If you're weighing this decision as a first-time buyer, it's also worth reviewing budgeting reality for fixer-uppers versus move-in ready homes before you get too far into either search.
Questions people ask
Is this inspection report as bad as it looks? Should we ask the seller to fix this, or is that asking too much?
Every house has something in the inspection report, and a long list isn't automatically a reason to walk away. I usually recommend going line by line, asking what each issue actually means, what it would cost to fix, and whether it's reasonable to ask the seller to address it given the price point and the current market.
What happens if the appraisal comes in low?
If the appraisal comes in below the agreed purchase price, you generally have a few options: renegotiate the price with the seller, cover the gap in cash, or in some cases challenge the appraisal with additional comparable sales. On renovation loans, this risk is higher because there may not be good finished comps nearby, which is exactly why I'd want to talk through financing type before you write the offer, not after.
How do I make my offer stand out without overpaying? Do you think the house is worth what they're asking?
More inventory doesn't mean every home is overpriced. In August 2026, homes in Salem-Keizer still closed at 99.7% of list price on average, so a low offer isn't automatically the winning strategy. Whether a specific house is worth its asking price depends on the property itself: condition, lot, location, and what a real contractor bid or comparable sale actually shows, not price per square foot alone.
Honestly, one of my favorite parts of this job is sitting down with a buyer before they've written an offer and running these numbers together, whether that's a fixer-upper bid or a move-in ready comparison. If you're weighing two specific listings right now and want a second set of eyes on the real math, feel free to get guidance on your specific fixer-upper or move-in ready decision. No pressure, just information, and a spreadsheet if you want one.
Hannah Fouts-Sparks
Broker, Sparks Property Group at SMI Real Estate. Licensed in Oregon. Serving Keizer, Salem, and the Willamette Valley.
Hannah@SparksPropertyGroup.com · 971.218.6225
Connect with Sparks Property Group ↗
Member discussion